September 2023 San Mateo County Market Update

Rumana Jabeen • August 21, 2023

State of the Economy and Our Housing Market


As 2023 moves forward, this is a good time to provide some insight on the current state of the economy for California and the United States, as well as what some factors signal about the future of our housing market. We have a couple of media clips to share, and then will break down factors like unemployment, inflation, timing the market, mortgage rates vs. home sales and home prices, and share a tale of two markets.


Economic Indicators impacting the Housing Market

Alan Ratner, managing director of Zelman and Associates, joins ‘Squawk on the Street’ to discuss the housing market, the ‘velvet’ handcuffs of low mortgage rates, and more. There are really four key indicators he mentions.

First, there was a stronger than expected start to new home market, while re-sell/existing home market is frozen with low inventory and low transaction volumes. This is keeping the housing market a bit suppressed. There was a lot of anticipation there might be a big correction on home prices, but the tight inventory mitigated that – though currently low activity is keeping a cap on the market despite record low inventory and high demand. Second, while interest rates being lower would free up the market, there are other factors like job performance and overall economy strength that could mean that doesn’t really help. Lower interest rates aren’t the end-all-be-all. Third, he talks about the decrease of rental prices and the dynamic between renting and buying. While rent growth has slowed it hasn’t really declined, but given the lack of inventory, it’s keeping rents stable. Fourth, the pricing of materials for new construction has come down from the high 1-2 years ago and coming into the year made home builders optimistic, but generally speaking the cost has been sticky with labor costs high. There is a lot of new home construction activity, and demand is still high but transactions are low, so this is going to either force builder profit margins down or home prices up.

Where are rates headed? Will there be a crash?

Logan Mohtashami, HousingWire lead analyst, joins ‘Squawk Box’ to discuss skyrocketing mortgage rates, after the National Association of Realtors warned rates could hit 8% if the economy continues to show strength and the Fed hikes rates again, the impact on the housing industry, and more.

Mohtashami discussed how when mortgage rates tipped over 6%, our market really came to a grinding slow down. Presently, consumers are dealing with high home prices and high mortgage rates. Mohtashami is forecasting interest rates reaching up to 8%, but don’t expect a crash because of the velocity of the market.

Key Economic Indicators
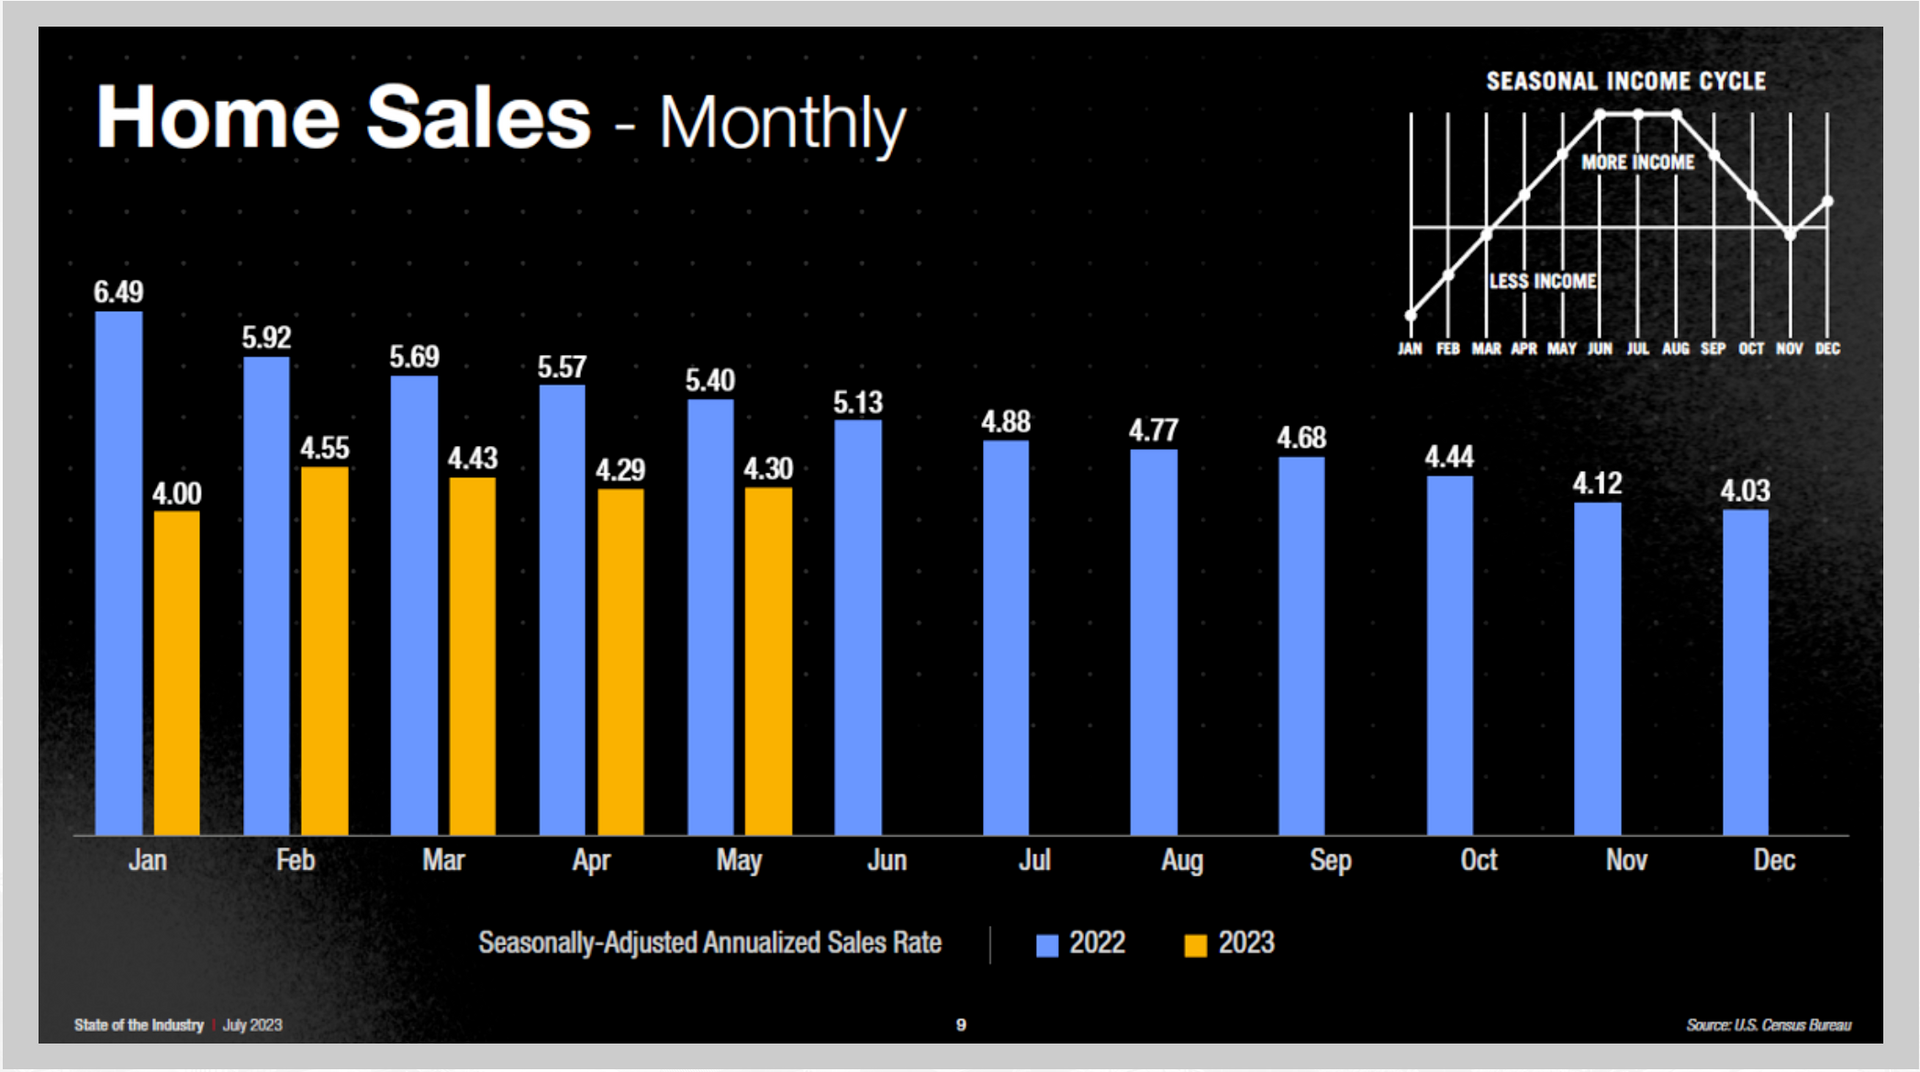
A graph showing home sales monthly in blue and yellow

Home sales are down month-over-month from 2022. There was anticipation of a correction on home prices, but tight inventory mitigated that. Presently, low activity and high interest rates are keeping a cap on the market despite record low inventory and steady demand.
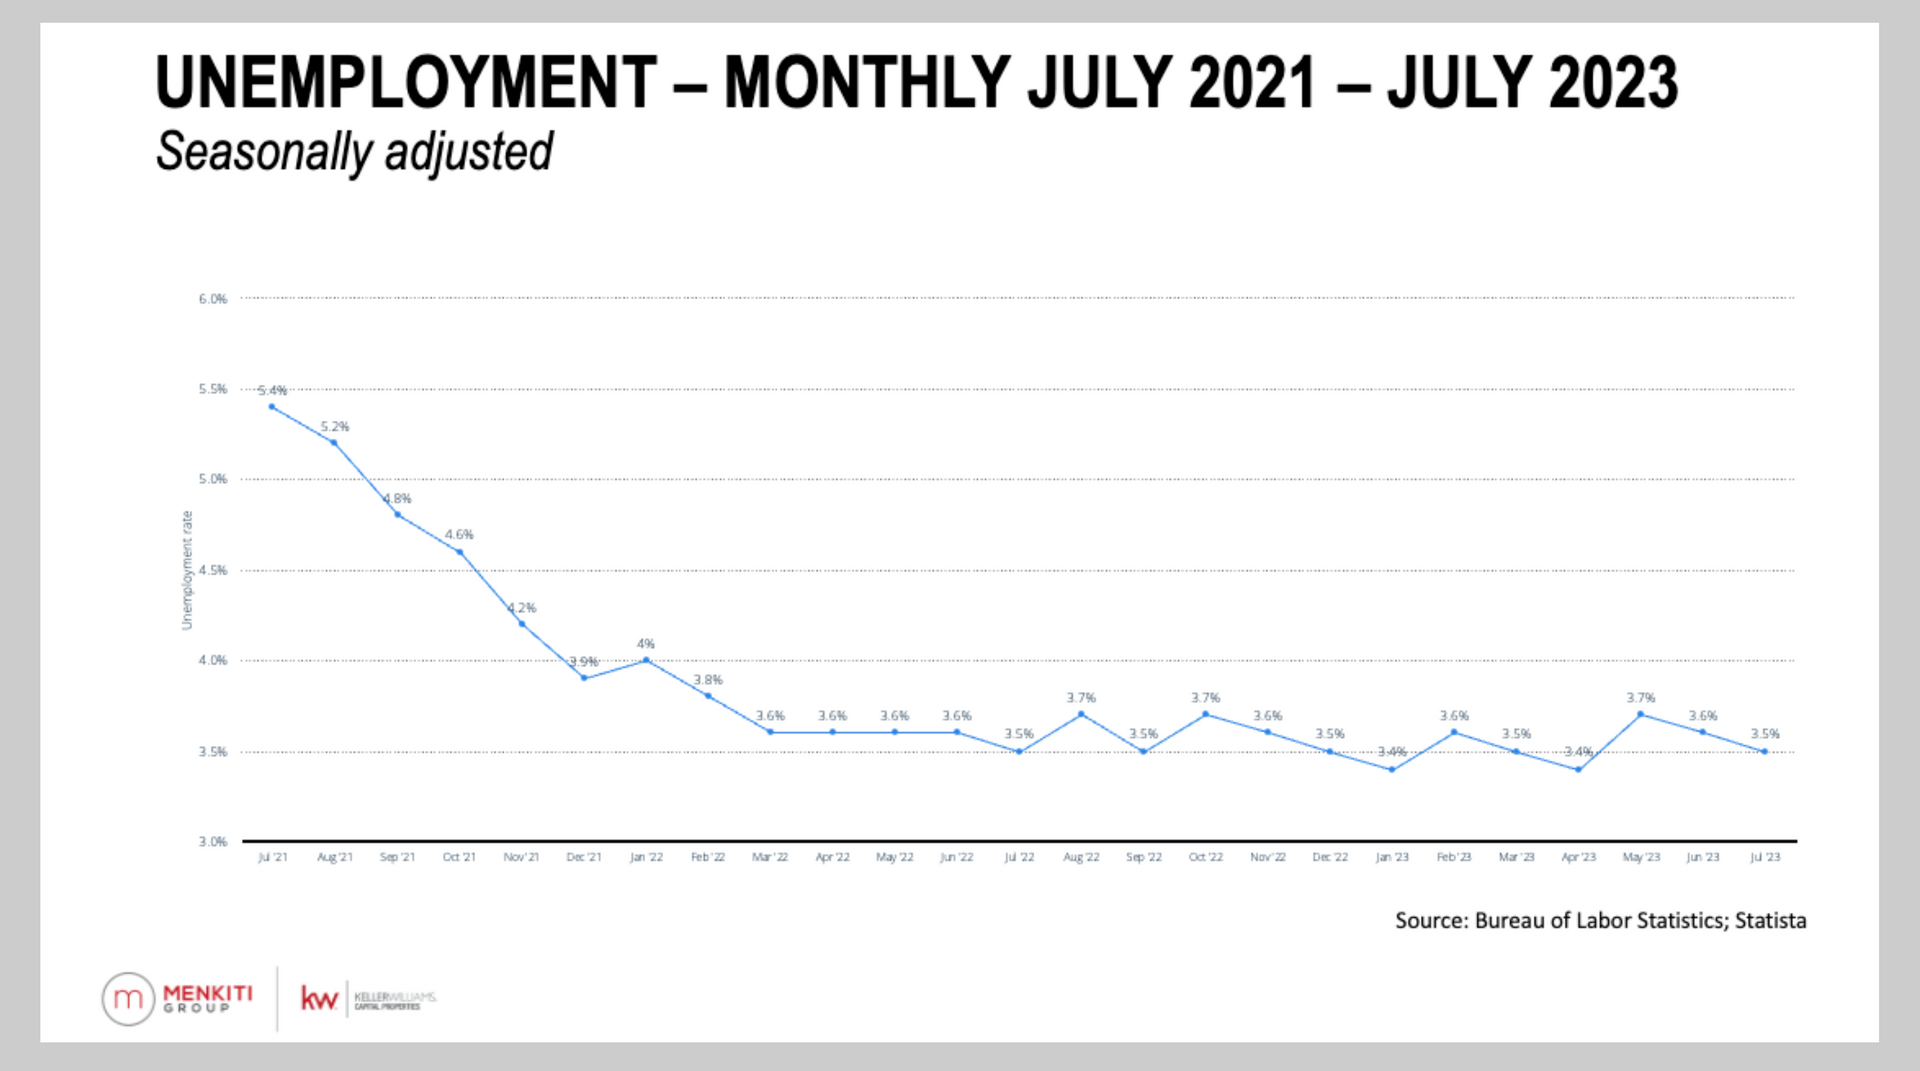
A graph showing unemployment monthly july 2021 - july 2023

We’re almost at full employment! The employment numbers haven’t gone up to keep up with the growth rate. As long as employment stays strong, and wages grow, the housing market could see more activity.
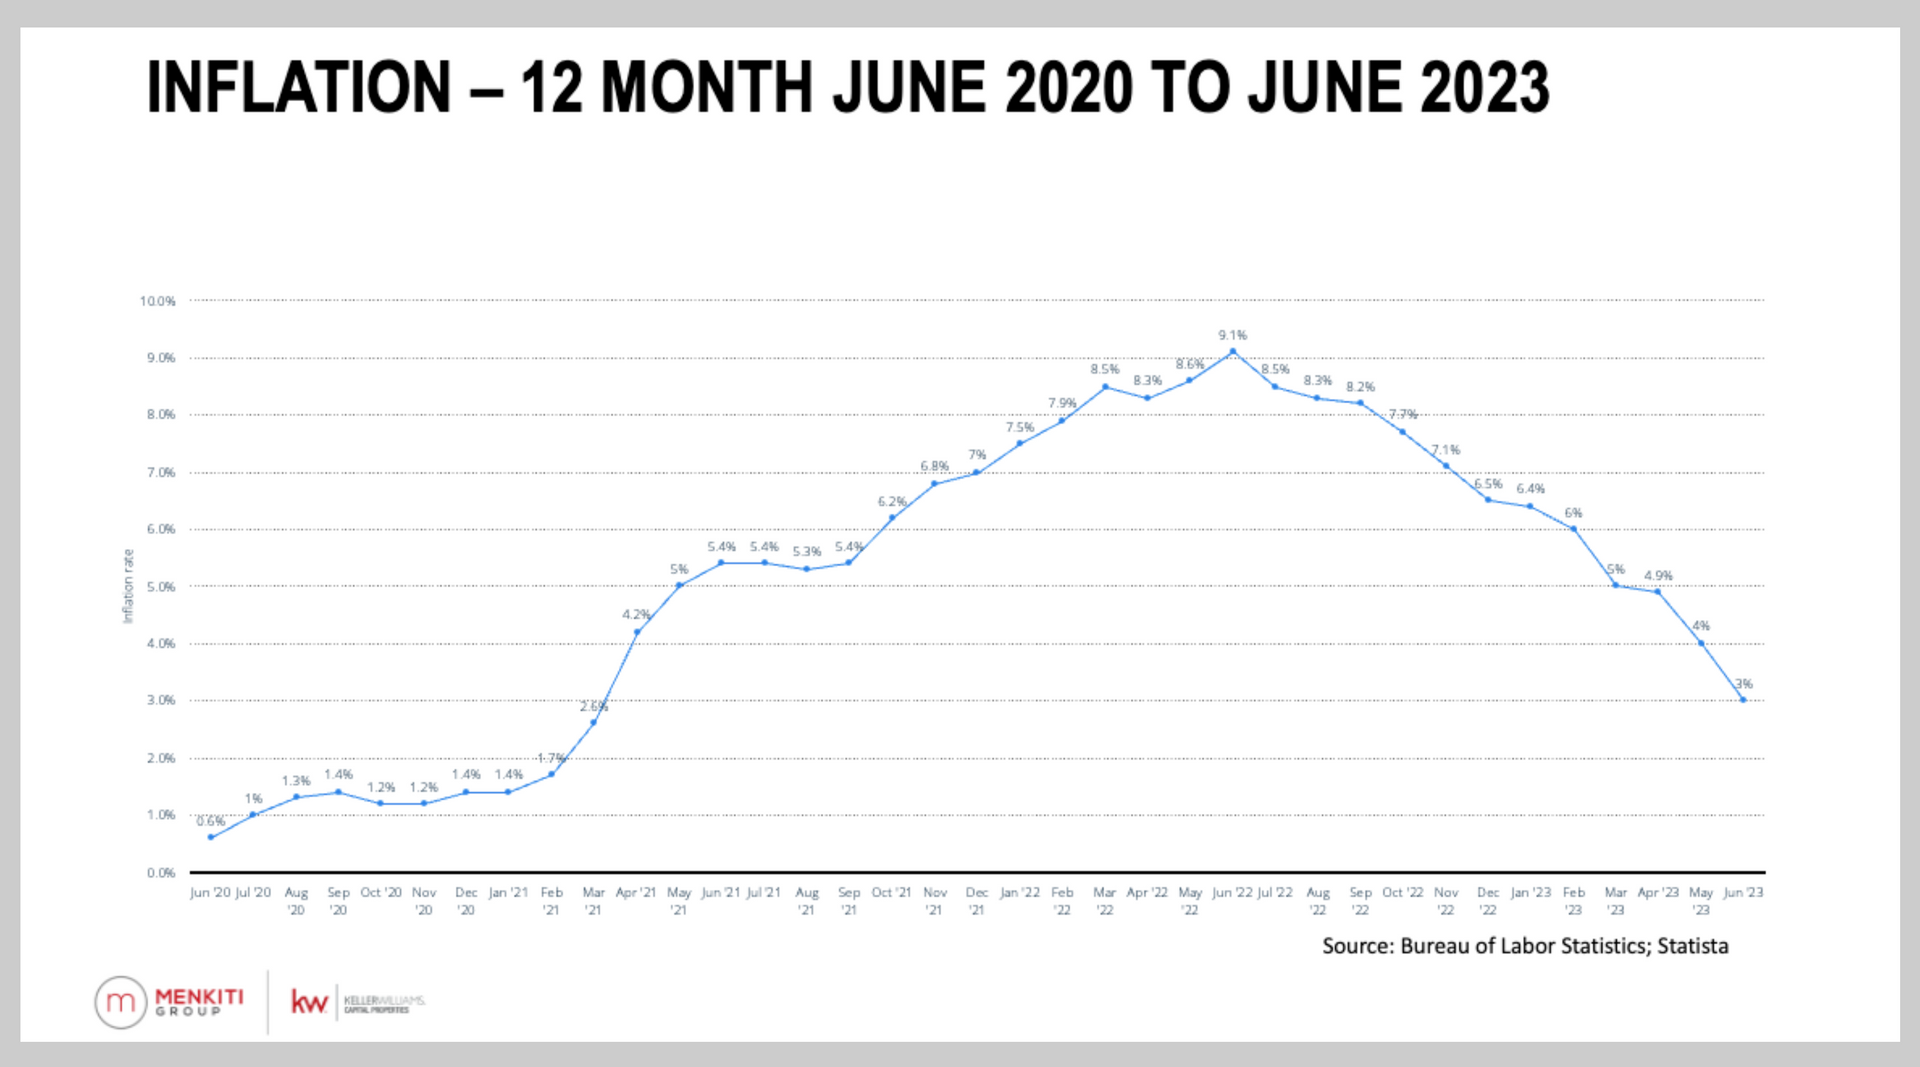
A graph showing inflation from june 2020 to june 2023

It’s been a year since there was the Inflation Reduction Act (IRA), and ideally we want to be at 2% Inflation. While we’re heading there, and all the market indicators are strong, we’re not there yet. We expect to see continued applied pressure to drive down inflation further, which means mortgage rates staying high, possibly even being pushed higher.
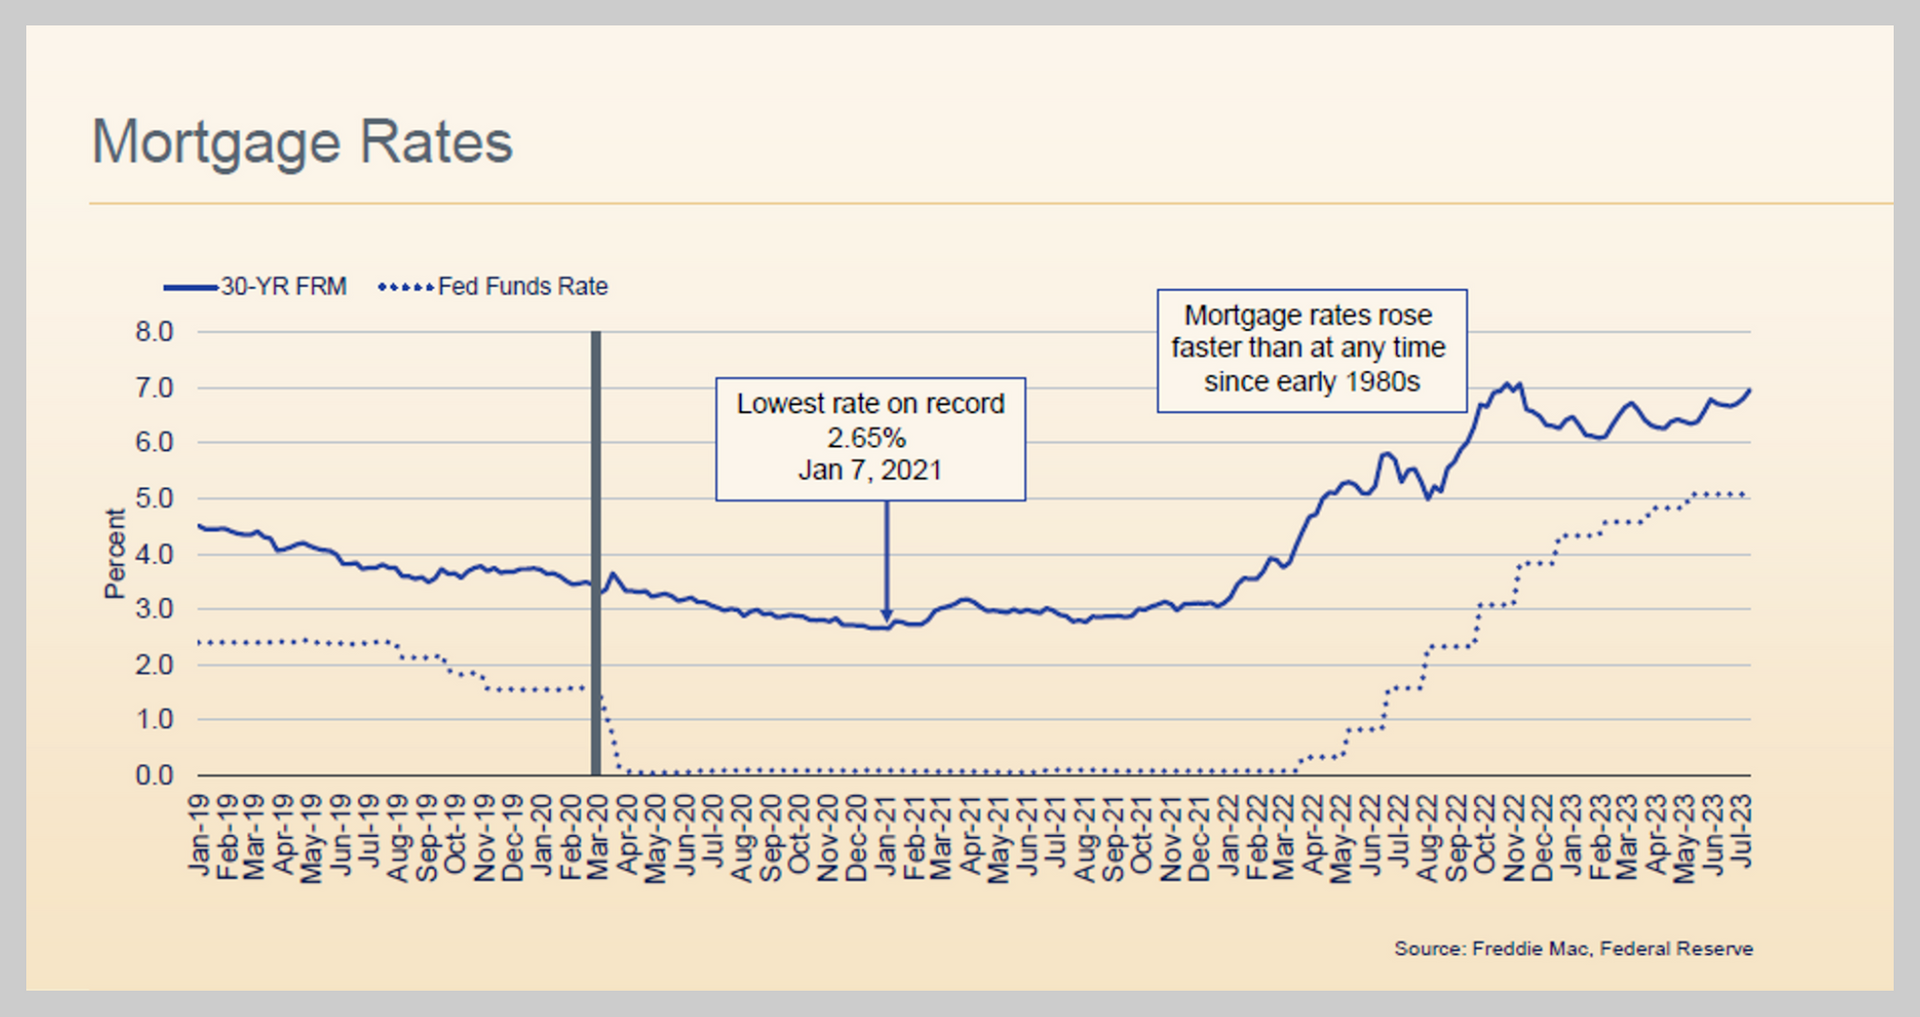
A graph showing mortgage rates going up and down

Housing prices will not plummet, There’s a major supply issue and very low home building, it’s all too low. It may become more stagnant, but there won’t be a plummet. 
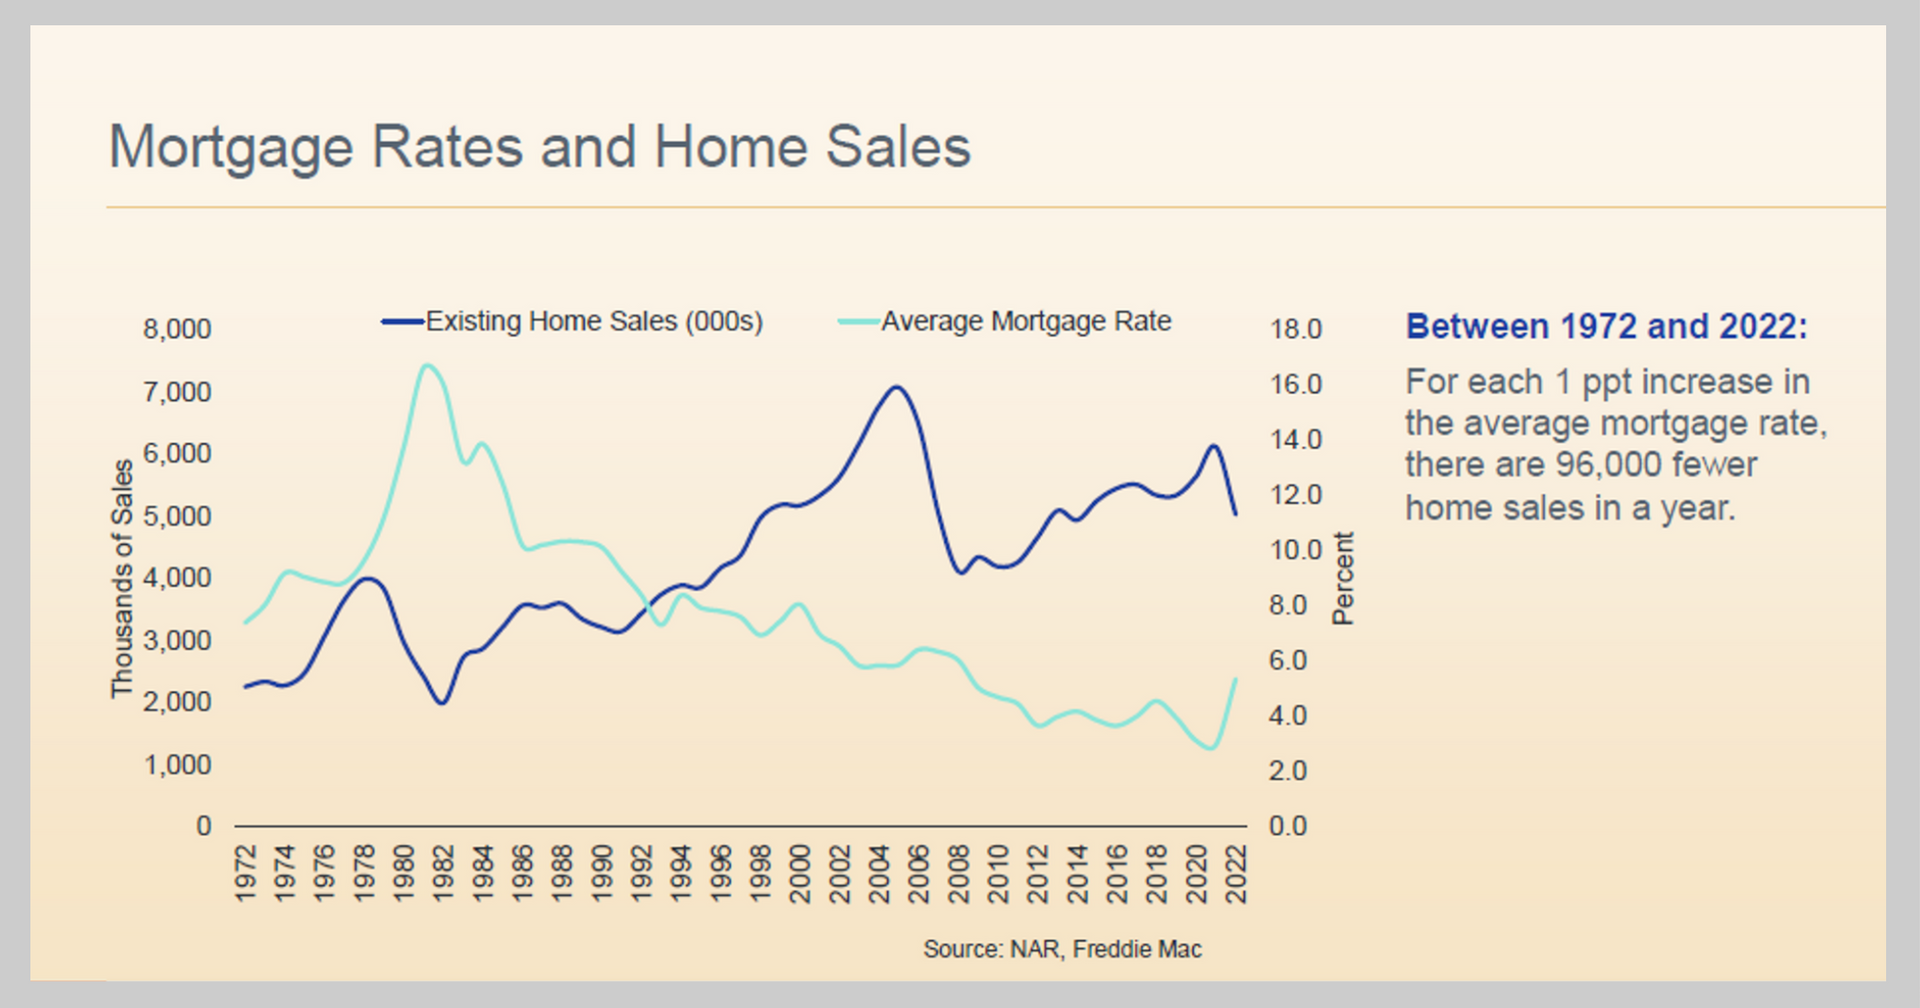
A graph showing mortgage rates and home sales between 1973 and 2020.
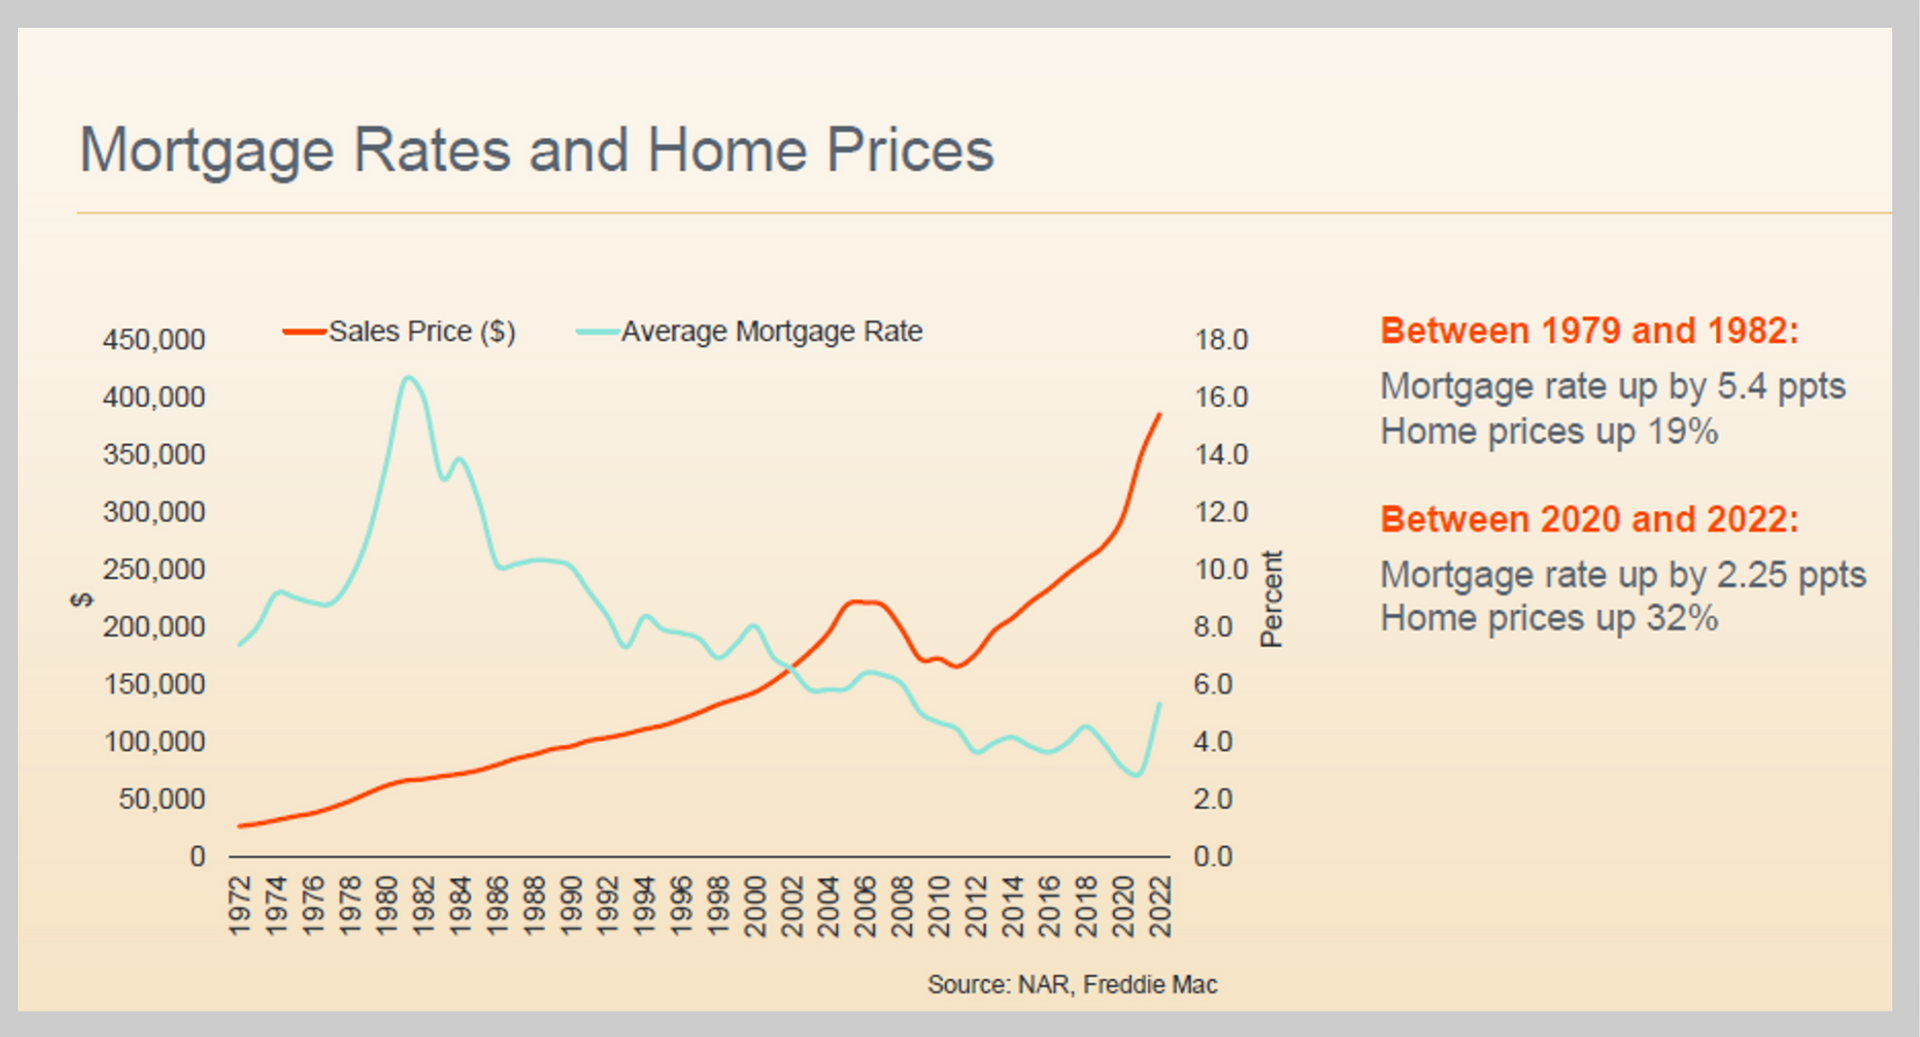
A graph showing mortgage rates and home prices

A Tale of Two Markets


In 2019, California was in a sluggish market with increased interest rates. The graphs below shows the effect of an interest rate rise. While home values increased 7%, the payments needed to fund the loan increased 45%. Additionally, many lenders now want to see appreciating income!

This is buying power reduced, and illustrated how much rates have impacted affordability in California with high housing prices and these boom and bust cycles.

In the bottom of each graph you can see indicated that most outstanding mortgagees (~80%) currently have a mortgage interest rate below 5%, and many more (~60%) have rates even below 4%. These homeowners velvet handcuffs and most are likely unwilling to “sell to buy” because they will have a much higher mortgage for their new home.
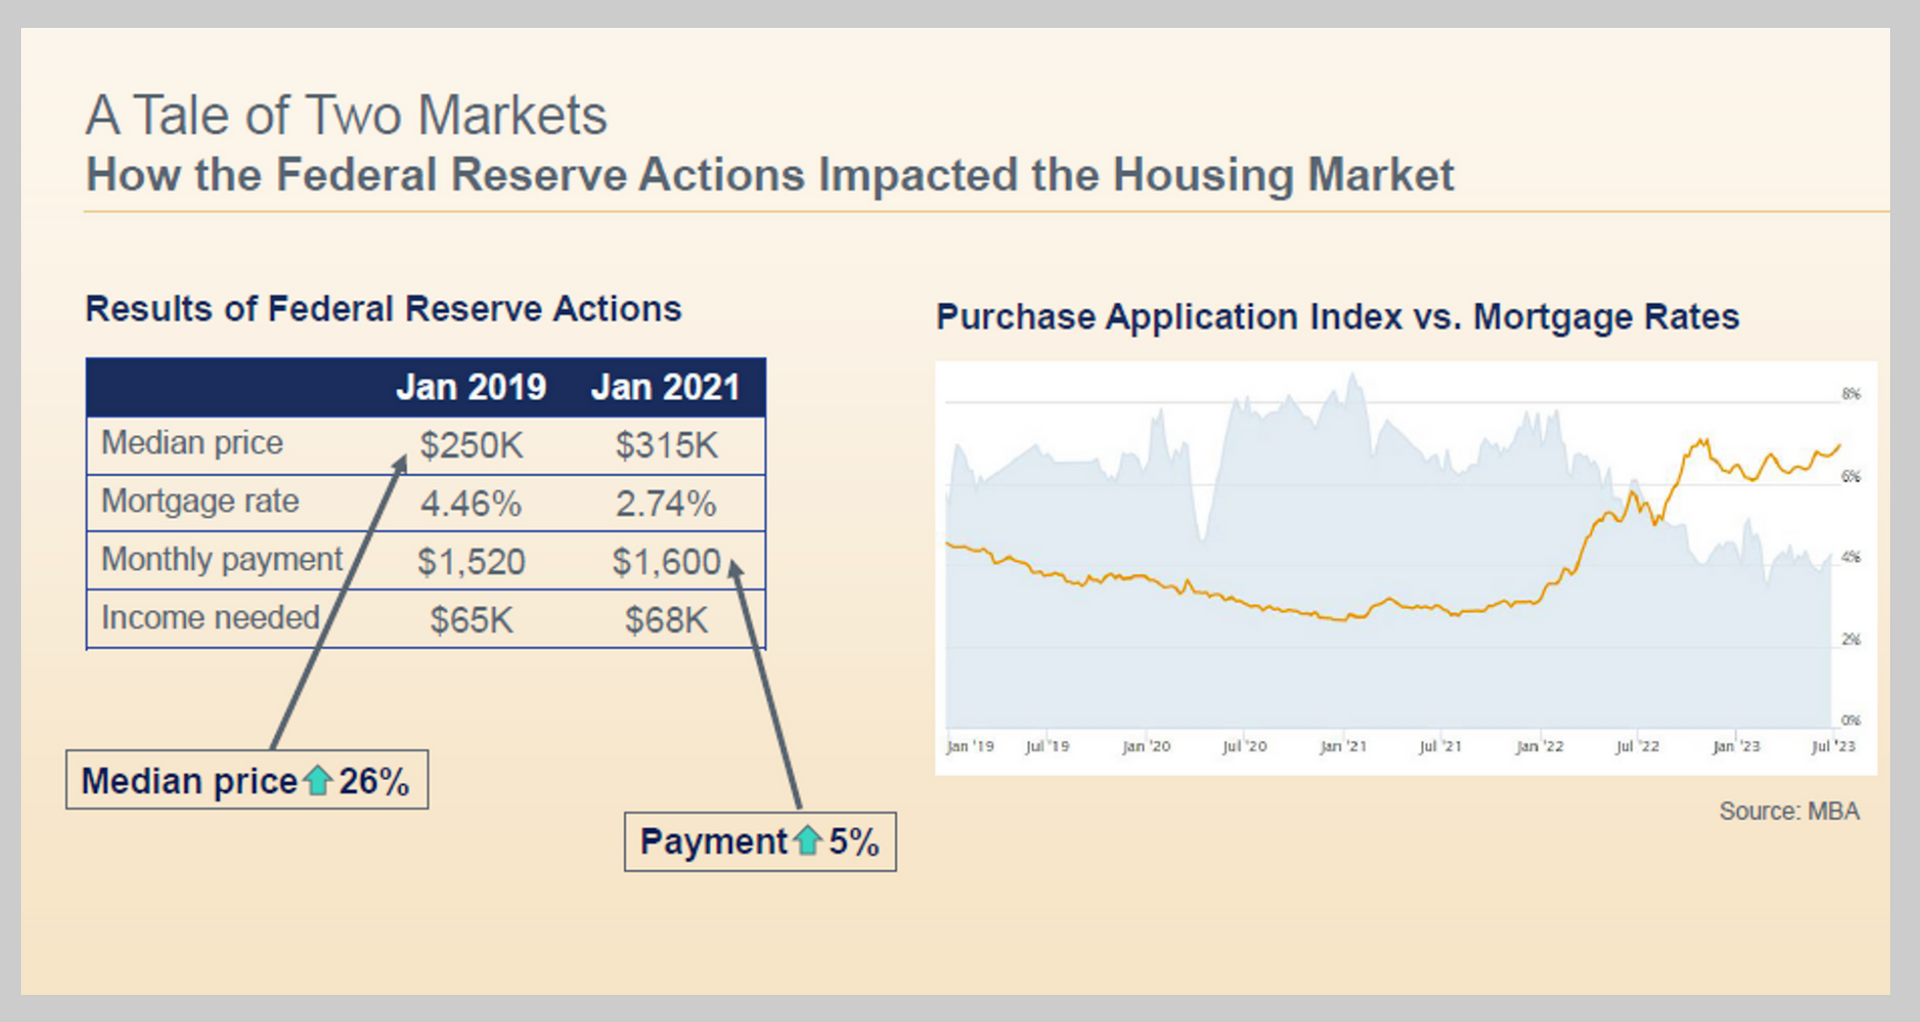
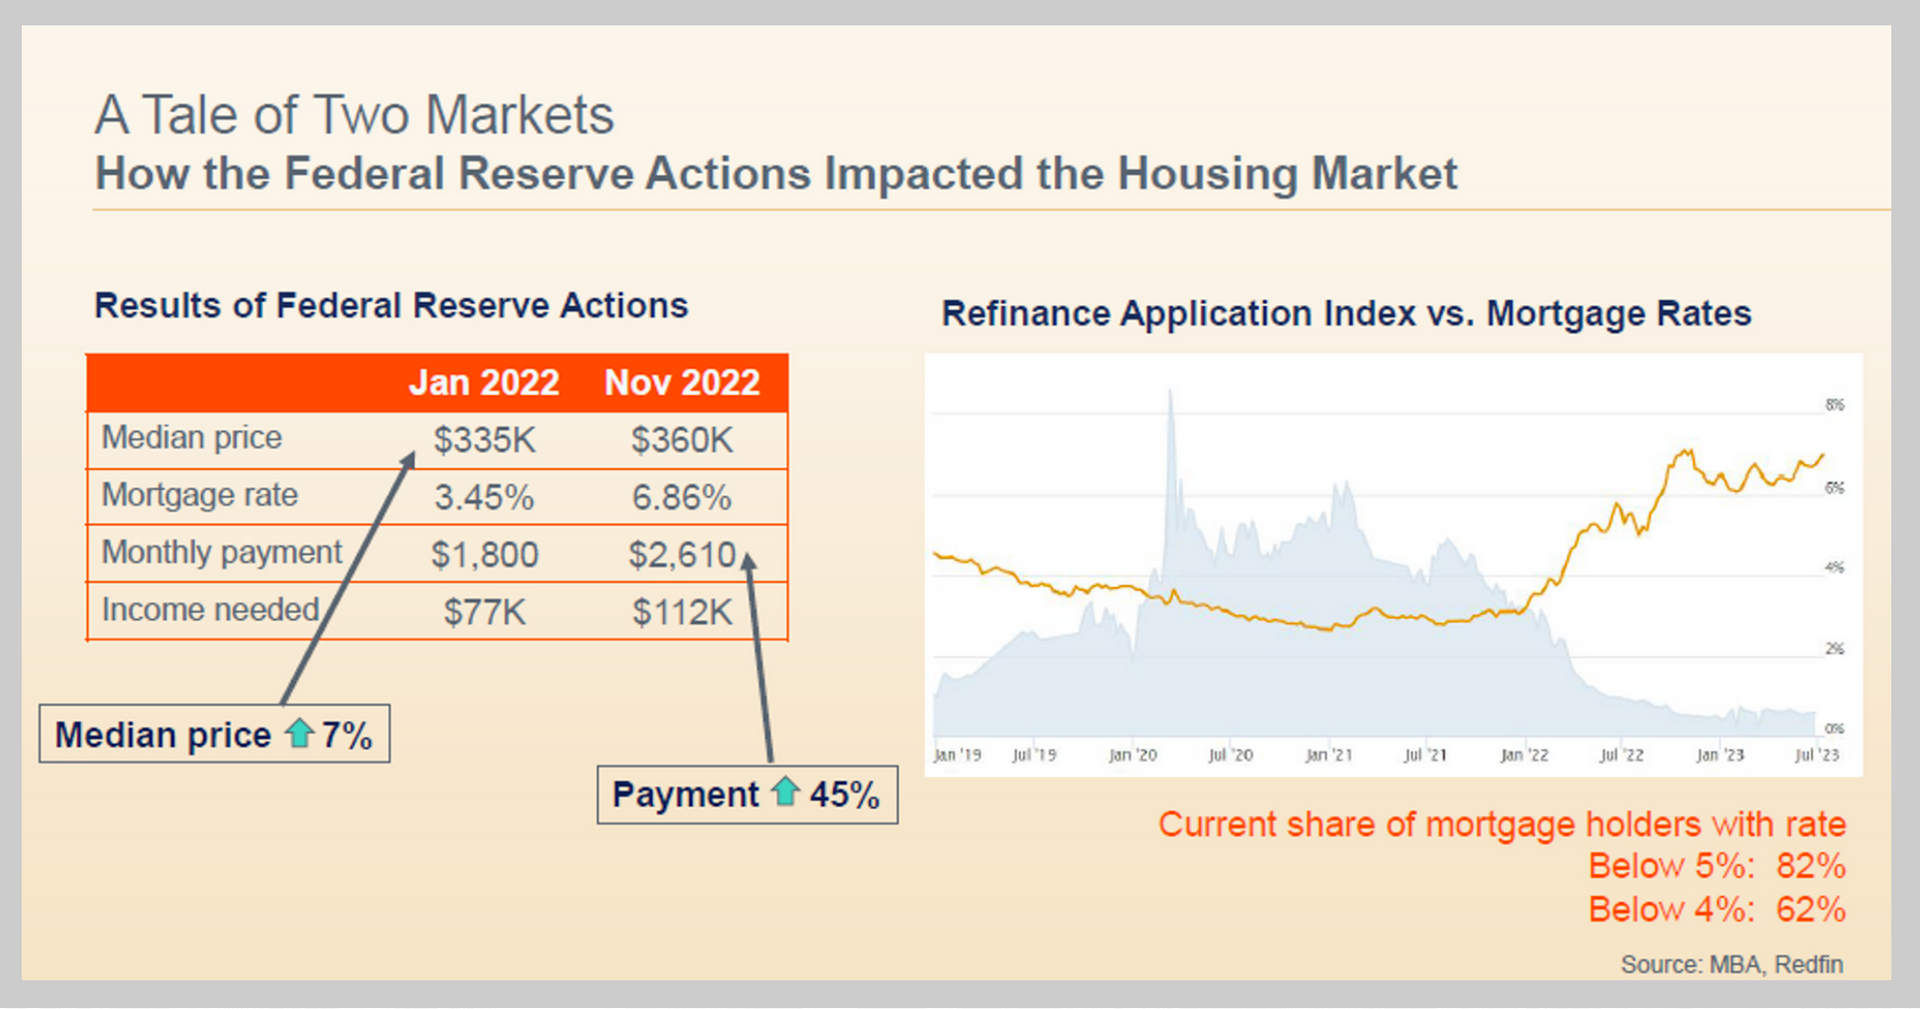
A table of two markets showing how the federal reserve actions impacted the housing market


My advice: Don’t try to time the market


We see this a lot with buyers waiting on interest rates to decline and inventory to increase, or maybe waiting on the full trifecta: housing prices falling, too. This is a dangerous game if you actually want to purchase and invest in the housing market. You’re likely to miss good inventory, current rates, and also equity being built in a home (which in our market averages ~6-8% y/o/y).

Where can you find additional financial support? There are products such as VA and FHA loans that are available to balance some of these factors, but they’re not being leveraged. Additionally, more traditional lenders are telling us about unique products and scenarios they’re handing. Some lenders are able to lock your rate for a brief period, even if you’re not yet in contract on a home.

Don’t pay the cost of waiting. Instead, assess your goals and financial situation. Speak with a lender to see what you could afford, and also a financial advisor who can help you make a good decision. Of course, contact me so you can understand the market and how you can be successful. I speak with buyers who often lament, “if only I’d bought in 2009” or “if only I’d bought in early 2020.” Don’t look back to today in a few years and still not be in a home.


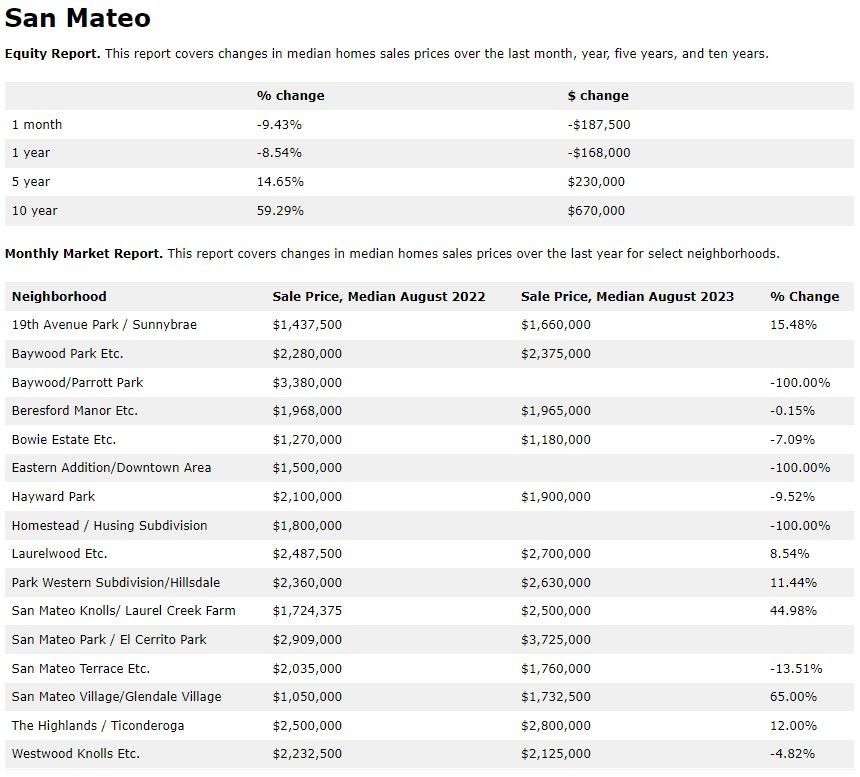
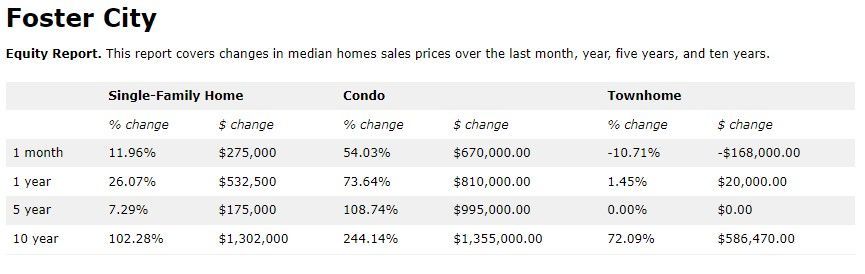
September 2023 Market Update and Equity Report
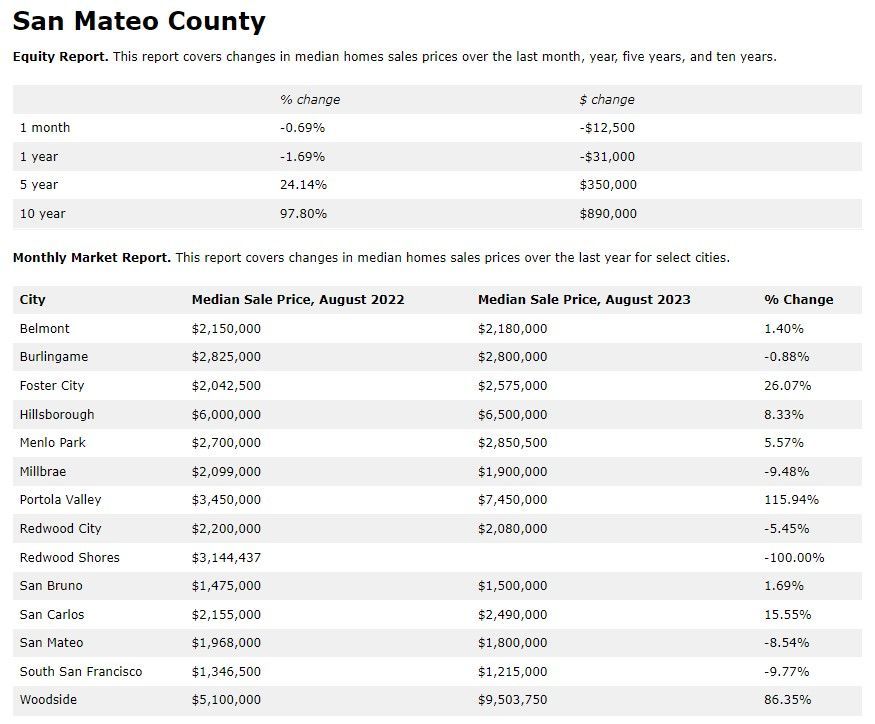

A screenshot of a san mateo county real estate report
A screenshot of a website showing a table for san mateo
A table with foster city written on it
By Rumana Jabeen • October 22, 2026
Rising mortgage rates are changing how buyers approach the market, but not everyone is feeling the pressure equally. Here's what that means for buyers and sellers across San Mateo County. Mortgage rates are climbing again, and naturally, I'm hearing questions about what this means for the Peninsula real estate market. Will buyers pull back? Will home prices soften? Will the demand we've seen throughout the year finally begin to slow? My answer is that it depends on which buyers and which homes we're talking about. Higher interest rates are certainly affecting affordability, but I'm seeing buyers respond in very different ways. Some are reconsidering their budgets or whether to buy at all. Others are bringing more cash to the transaction so they can continue pursuing the homes they want. We're not looking at one market moving in one direction. We're looking at several different markets, each responding to the same pressures in different ways. Buyers Are Changing Their Financing, Not Necessarily Their Goals I recently helped a buyer get into contract who was initially planning to make a substantial down payment. As their stock investments performed well, they decided to sell additional shares and increase their down payment to 48% of the purchase price. Their goal wasn't to purchase a more expensive home. It was to reduce the amount they needed to borrow and keep their monthly mortgage payment comfortable. I'm seeing something similar with another buyer who has a maximum purchase price of $2.6 million. Despite rising rates, they haven't lowered that ceiling. Instead, they're evaluating how much additional cash they can bring to the transaction to offset the higher borrowing costs. These are two examples of something important happening in our market. Buyers with significant financial resources have options that other buyers simply don't. They may have stock investments, substantial savings, or equity from a previous home that allows them to adjust their financing without compromising their home search. With the tremendous wealth being generated in the technology sector, including the potential for additional liquidity from future AI company IPOs, that financial flexibility is particularly relevant in the Bay Area. But not every buyer has those options. One Market, Very Different Pressures For buyers shopping at the more accessible end of the single-family home market, higher rates can change everything. A buyer who was previously comfortable competing for a particular home may now find that the monthly payment stretches their budget too far. Some will lower their price range. Others will reconsider whether homeownership makes financial sense right now. That changes the competitive landscape for sellers, too. If your home is positioned toward first-time or more payment-sensitive buyers, I still expect strong interest when it's priced appropriately. But where you might previously have attracted ten offers, some of those buyers may now be looking at less expensive homes or stepping out of the market. You may still sell above asking, but that doesn't necessarily mean you'll achieve the same premium you might have seen when borrowing costs were lower. At the higher end of the market, particularly around $3.5 million and above, I'm seeing a different dynamic. Many of these buyers have greater financial flexibility and can increase their down payments to manage their monthly obligations. That doesn't make luxury homes immune to changes in interest rates, but it can make their buyers less sensitive to those changes. For sellers, this is why understanding your likely buyer matters so much. The strategies that work for a $1.8 million home may look very different from those for a $4 million home. The Condo and Townhome Question Is Getting More Complicated When single-family homes become less affordable, it's natural to assume buyers will turn toward condos and townhomes. Some will, but I'm not convinced we'll see a significant migration into those property types. In my experience, many buyers who are committed to owning a single-family home would rather wait than purchase something that doesn't meet their long-term needs. There's also another consideration that condo and townhome buyers need to understand. California recently enacted Assembly Bill 2050, which will establish stronger reserve-funding requirements for homeowners associations beginning in 2032. The goal is to help associations maintain sufficient reserves for major repairs and future expenses. For some communities, meeting those requirements could eventually mean higher HOA dues or special assessments. The actual impact will depend on each association's financial position, existing reserves, and future obligations. This matters because a lower purchase price doesn't necessarily translate into a lower cost of ownership. A condo may look considerably more affordable than a single-family home, but buyers need to consider the mortgage payment, property taxes, insurance, HOA dues, and potential future assessments together. I also expect buyers to become increasingly attentive to HOA financial health, which could influence how they evaluate individual properties and communities. That doesn't mean condos and townhomes are bad investments. It means understanding what you're buying has never been more important . What I'd Advise Buyers and Sellers Right Now For buyers : Start with the monthly cost you can comfortably sustain, not simply the maximum purchase price a lender will approve. If you're considering a larger down payment, evaluate that decision alongside your need for cash reserves and financial flexibility. If you're exploring condos or townhomes, read the disclosures carefully, particularly the HOA budget, reserve study, meeting minutes, and any planned assessments. Understand the total cost of ownership before making a commitment. And if higher rates have changed what you can afford, don't feel pressured to buy something that doesn't meet your needs simply because you want to become a homeowner. Sometimes the right strategy is to adjust your search. Sometimes it's to wait. For sellers : Don't assume strong overall buyer demand guarantees the same outcome for every property. The most important questions are who your likely buyers are, how they're financing their purchases, and how changes in affordability affect the price range in which your home competes. A carefully prepared and strategically priced home can still perform exceptionally well. But today's market requires us to understand the financial realities of the buyers we're trying to attract. The Peninsula continues to offer tremendous opportunities, but those opportunities are becoming more specific to each property, price point, and buyer. The best time to start your strategy was yesterday. The next best time is today.
San Mateo county Fall
By Rumana Jabeen • September 23, 2026
For buyers, fall may finally bring more choices. For sellers, those homes are arriving in front of a large and motivated pool of buyers who have been waiting for them.
By Rumana Jabeen • August 20, 2026
Summer didn't bring enough new homes to meet buyer demand. Now, a growing pool of motivated buyers could be setting the stage for a very active fall across San Mateo County. Summer is winding down, and normally this is the point when I look back at the season and see a market that has taken a bit of a breather. This year, I see something different. We did get some new inventory over the summer, but not nearly enough to keep pace with demand, particularly for single-family homes. At the same time, buyers never really went away. Many are financially prepared, motivated, and actively searching, but they simply haven't found the inventory they need. That leaves us heading toward fall with an interesting combination: limited supply, persistent demand, and buyers who are becoming increasingly eager to make a move. I don't know yet exactly how the fall market will play out, but the ingredients are in place for a very active season. Summer Never Delivered the Inventory We Needed Summer usually gives buyers more choices. New listings arrive, activity spreads across more properties, and the market tends to settle into a somewhat more relaxed rhythm. That wasn't really the story this year. Single-family home inventory remained particularly tight across San Mateo County. When desirable homes did come to market, buyers often competed aggressively for them. Since May 1, 1,067 single-family homes have sold across San Mateo County. Of those, 798 sold above their asking price, and 125 sold for at least 120% of asking. That tells me something important. Demand isn't missing. In many cases, buyers simply haven't had enough homes to choose from. We're seeing an even more extreme version of that dynamic in San Francisco, where more than 140 homes sold for at least $1 million above asking during the first half of 2026. That is an extraordinary increase from only eight such sales during the same period last year. San Mateo County is its own market, and I would never suggest that San Francisco's results automatically translate to the Peninsula. But both markets demonstrate what can happen when motivated buyers compete for limited desirable inventory. Where Did All the Buyers Go? They are still here. I'm currently working with three highly motivated buyers who are financially prepared and ready to purchase. Their challenge isn't deciding whether they want to buy. It is finding the right single-family home to buy. And they are certainly not alone. Every buyer who spent May, June, July, and August waiting for the right property does not simply disappear when summer ends. Many carry that search into September and October with even greater motivation. That is the pent-up demand I am watching now. If fall brings a meaningful increase in new listings, we could see that demand spread across a healthier selection of homes. If inventory remains constrained, competition for the best properties could become even more pronounced. Either way, buyers should be preparing now rather than waiting for the fall market to officially "begin." Sellers, You Haven't Missed Your Window For homeowners, I think this is the most important takeaway from the summer. If you considered selling earlier this year but didn't, you haven't necessarily missed your opportunity. In fact, time may be on your side. There is a pool of buyers who have spent months searching without finding the right home. If your property matches what those buyers have been waiting for, coming to market this fall could put you in front of an unusually motivated audience. That does not mean every home will automatically receive multiple offers or sell substantially over asking. The fundamentals still matter. Your price has to match your product. Your home has to be positioned against the other choices buyers have across the Peninsula, not just the house down the street. Presentation, condition, location, and pricing strategy will determine whether buyers see your home as the opportunity they've been waiting for. A strong market can create opportunity, but strategy is what converts that opportunity into a successful sale. Advice for Buyers This Fall If you have been waiting for more inventory, use the remaining weeks of summer to get completely prepared. Make sure your financing is current, know your true comfort range, and be clear about which features are essential versus negotiable. More homes may come to market this fall, but the best single-family properties are unlikely to sit around waiting for you to decide. Patience has been necessary this summer. This fall may require decisiveness. Advice for Sellers This Fall If you have been wondering whether you waited too long to sell, let's change the question. Instead of asking whether you missed spring or summer, ask what your specific home would be competing against if it came to market this fall. That is something we can evaluate now. We can look at recent sales, current inventory, buyer activity, your home's condition, and where it fits within its price bracket. If the opportunity is there, the next few weeks give us time to prepare intentionally rather than rushing to market. Summer left us with fewer homes for sale, not fewer buyers. That distinction could define the fall market. The best time to start your strategy was yesterday. The next best time is today.
By Rumana Jabeen • July 16, 2026
Rumana Jabeen and Burt Tsuei recently compared notes on what they're seeing across Foster City, San Mateo, and the Peninsula. These are the questions they're hearing most often.
By Rumana Jabeen • June 12, 2026
Why understanding your options, and your market, can open more doors than you think.
By Rumana Jabeen • May 9, 2026
Why Some Peninsula Homes Are Getting 20 Offers While Condos Sit Unsold
By Rumana Jabeen • April 20, 2026
This Market Is Not Slow. It’s Selective.  And Pricing Is Driving Everything
By Rumana Jabeen • March 5, 2026
A Small Interest Rate Shift, A Big Market Signal
Rumana Jabeen & Burt Tsuei
By Rumana Jabeen • March 5, 2026
Rumana Jabeen & Burt Tsuei announce their new working relationship.
By Rumana Jabeen • February 7, 2026
Even Though the Market Is Slow,  There Is Still a Lot to Love